Adult and child raking autumn leaves in a garden

5 Simple Fall Maintenance Tips Before Cold Weather

Now that autumn is here, it’s time to go over our top 5 fall maintenance tips for homeowners. Make sure you tackle these items in the next few weeks to make sure your home is ready for the winter months!
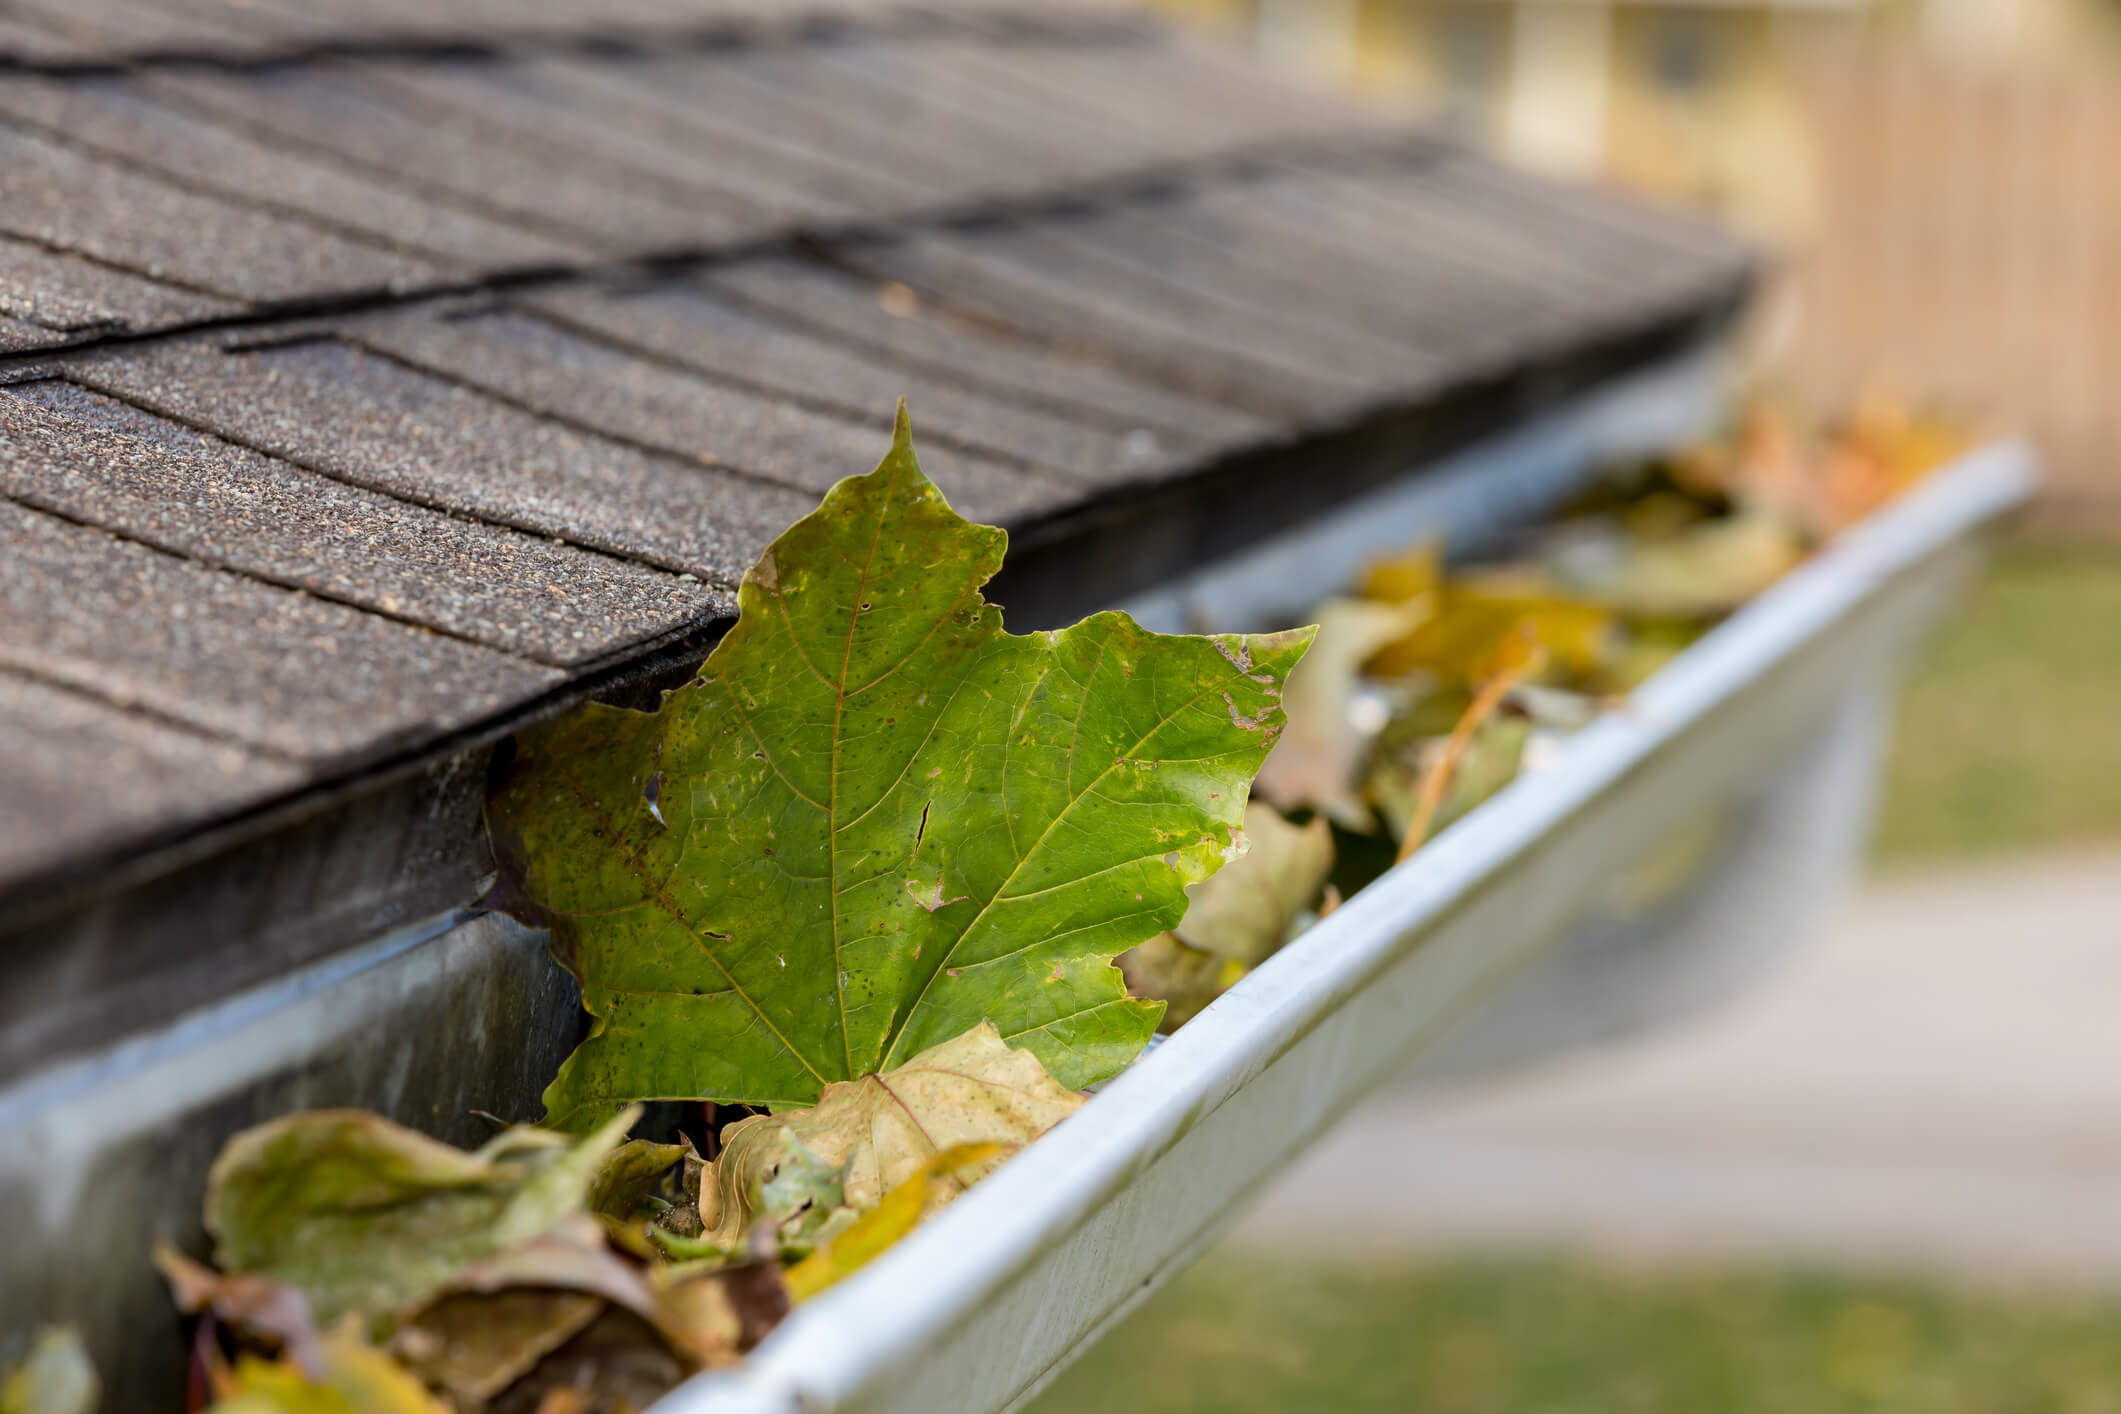
 

Leaves collecting in a gutter beside a roof edge

1. Clean your gutters

The first of our fall maintenance tips is to take care of your gutters. Clogged gutters can cause costly damage in the long run! Remove debris and fallen leaves to make sure your gutters don’t get clogged. An old spatula works great for getting into these small spaces.
 

Person holding a smoke alarm against a softly blurred living room

2. Check your detectors

The next one of our fall maintenance tips isn’t just for autumn. In fact, checking your smoke alarms and carbon monoxide detectors should be on your list every season. Make sure your batteries are still working and the expiration dates on your alarms haven’t passed.
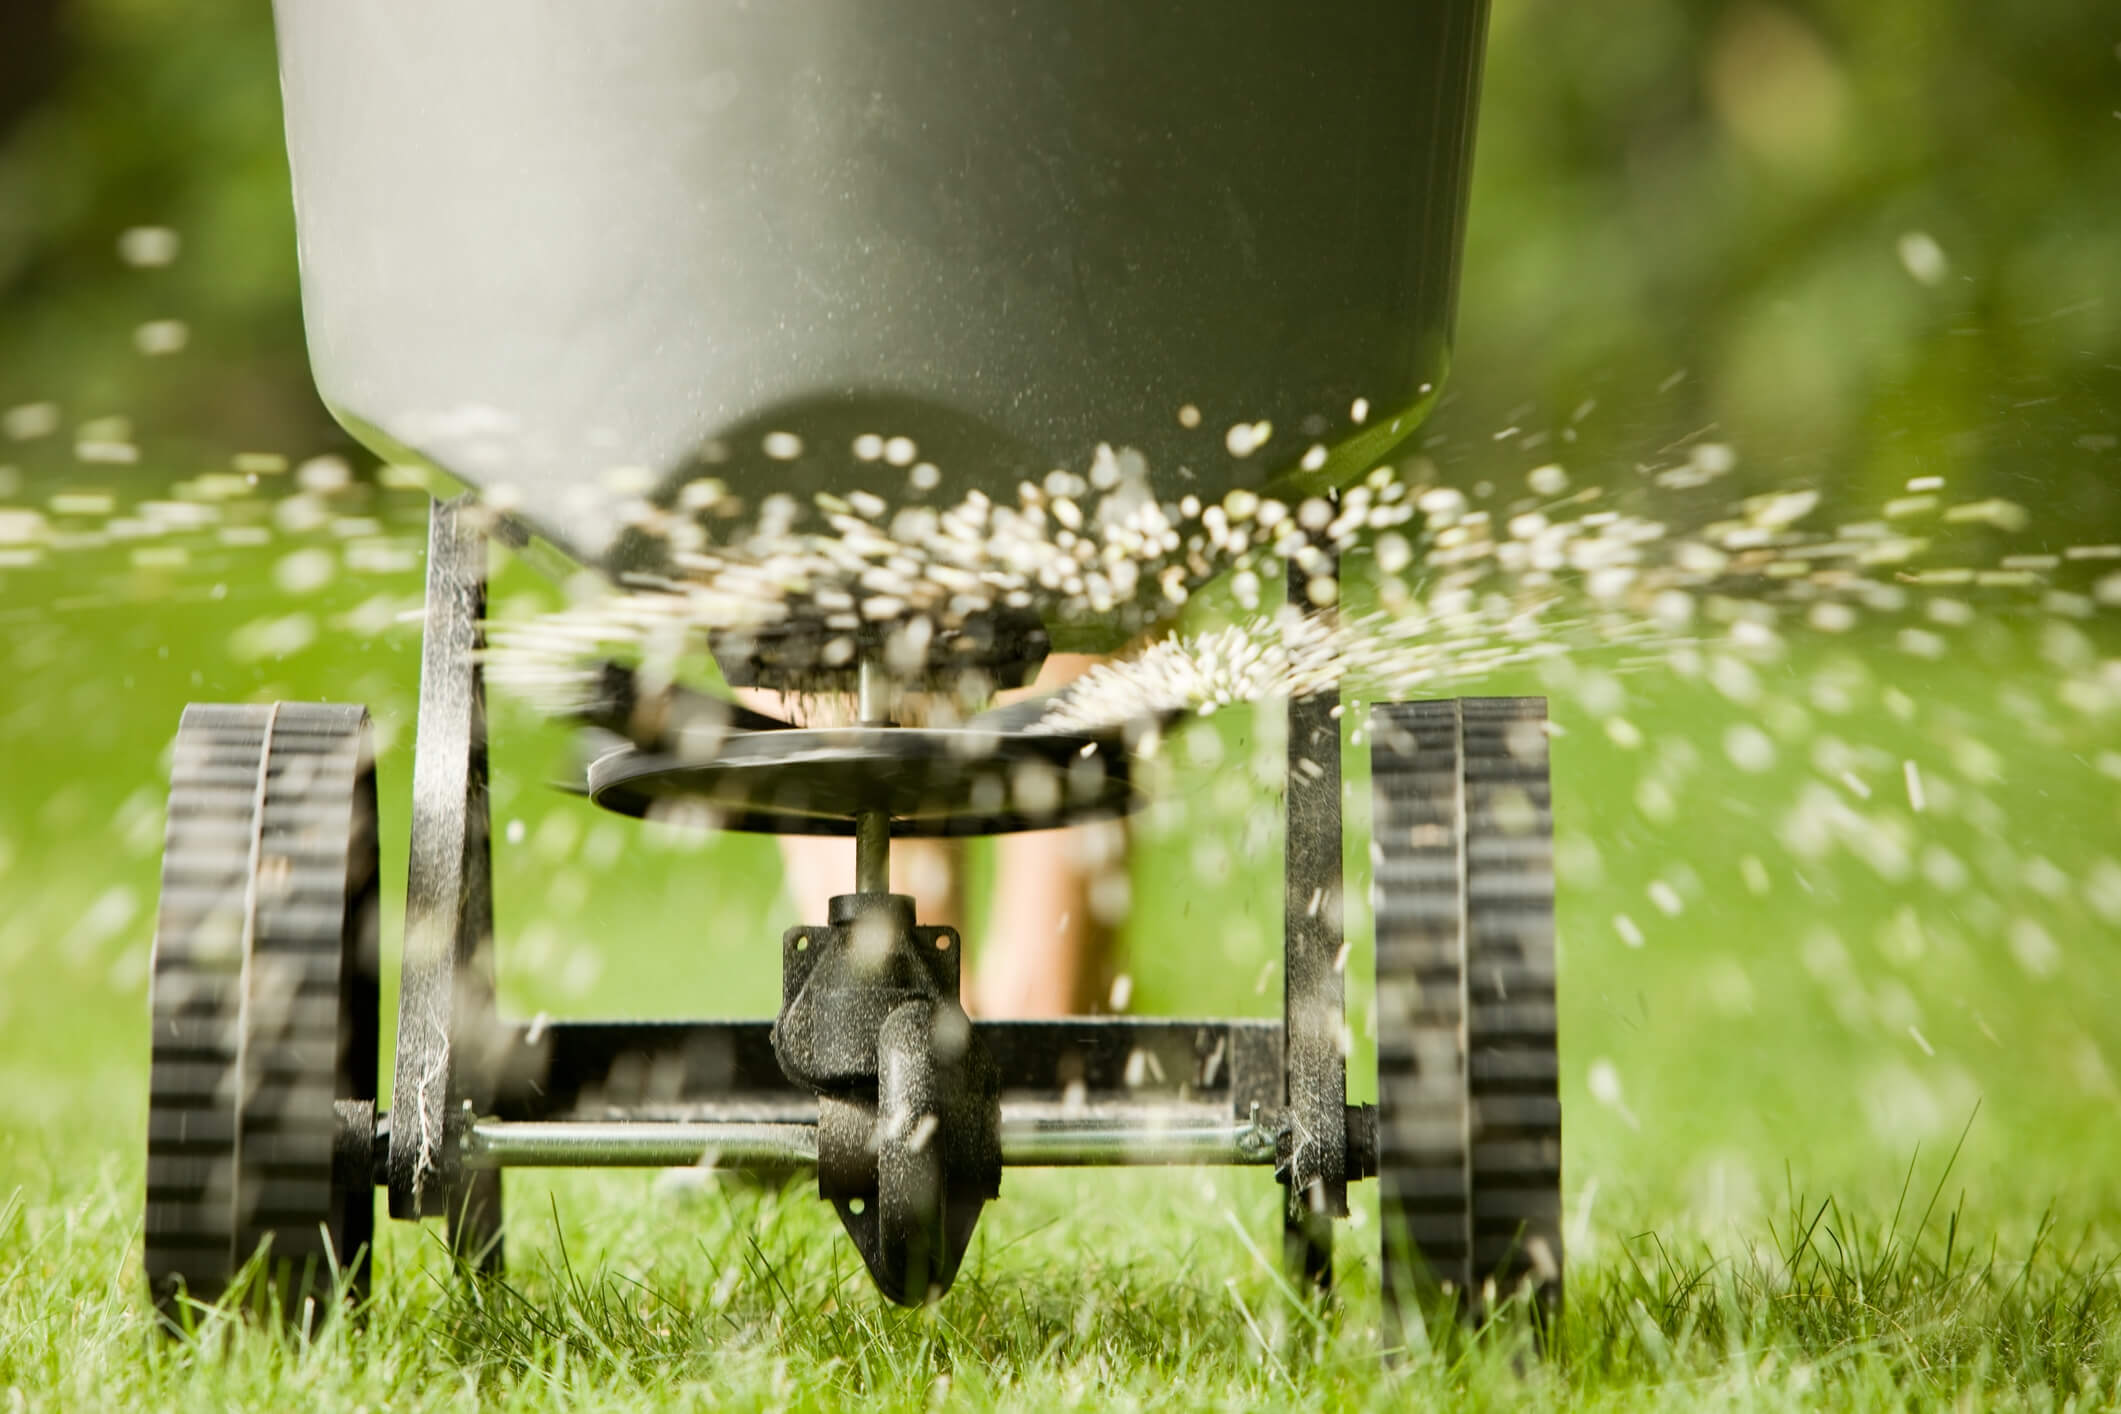
 

Lawn spreader scattering material across green grass

3. Fertilize your lawn

Next, you should consider fertilizing your lawn this fall. Now is the perfect time to give your lawn extra nutrients before it goes dormant for the winter.
 

Sprinkler watering a lawn in the sunshine

4. Winterize your sprinkler system

Whether your pay someone to come blow out/turn off your sprinkler system or you do it yourself, now is the ideal time to get your sprinklers ready for winter. You don’t want winter freezes to cause damage to your sprinkler system!
 

Adult and child cleaning dishes together at a kitchen sink

5. Deep clean

Now is a great time to give your home one last deep clean before the cold weather creeps in. Open up some windows and give your bedrooms, kitchen, and bathrooms one final deep clean with fresh air flowing before we need to keep everything closed up for the winter.
 

Family standing with bicycles beside a grassy trail

Fall maintenance tips courtesy of Challenger Homes

You’ll love living in a Challenger home, no matter what season it is! For more information on our current communities in Colorado Springs and Northern Colorado, please contact us today.

← Back to News & Resources

How we estimate your payment

Principal & interest + estimated property taxes + homeowners insurance + applicable HOA/metro charges.

Our advertised estimated lowest payments use a 30-year VA loan example for an eligible buyer with full entitlement and 0% down. The featured payment option is 3-2-1 Buydown. Advertised amounts are year-one estimates; payments increase in years 2, 3 and 4. The note rate is fixed at 6.5%. Home price, estimated taxes, and HOA/metro charges vary by property and community. Open the asterisk beside a payment for that home’s figures and assumptions.

More about the calculation

Principal and interest are calculated from the modeled loan amount, selected payment rate, and loan term. The model uses 8.661% combined 3-2-1 buydown cost and an assumed 2.15% VA funding fee financed into the loan. It includes a $8,000.00 closing-cost allowance, modeled through a higher contract price and seller credit. Points and any temporary buydown funding are modeled through a higher contract price and seller credits, subject to lender approval and appraisal support.

Property taxes use the community mill levy and an approximate assessed-value calculation; they are estimates, not an actual tax bill. Homeowners insurance is estimated at $180.00 per month. Applicable community HOA/metro charges are included. Upfront tax and insurance escrow deposits are excluded. A zero down payment does not guarantee zero cash due at closing.

3-2-1 Buydown payment assumption notes

The advertised amount is the Year 1 estimated payment. A builder-funded 3-2-1 buydown reduces the buyer's principal and interest payments during the first three years; the underlying note rate remains fixed. Payments are based on a rate 3 percentage points below the note rate in Year 1, 2 points below in Year 2, and 1 point below in Year 3. Full note-rate payments begin in Year 4. Taxes, insurance and HOA/metro charges are estimates and may change. Interest rate is not APR. Financing costs are modeled through a higher contract price and seller credits, subject to lender approval and appraisal support. Contact the lender for a complete Loan Estimate.

Promotion terms & lender information