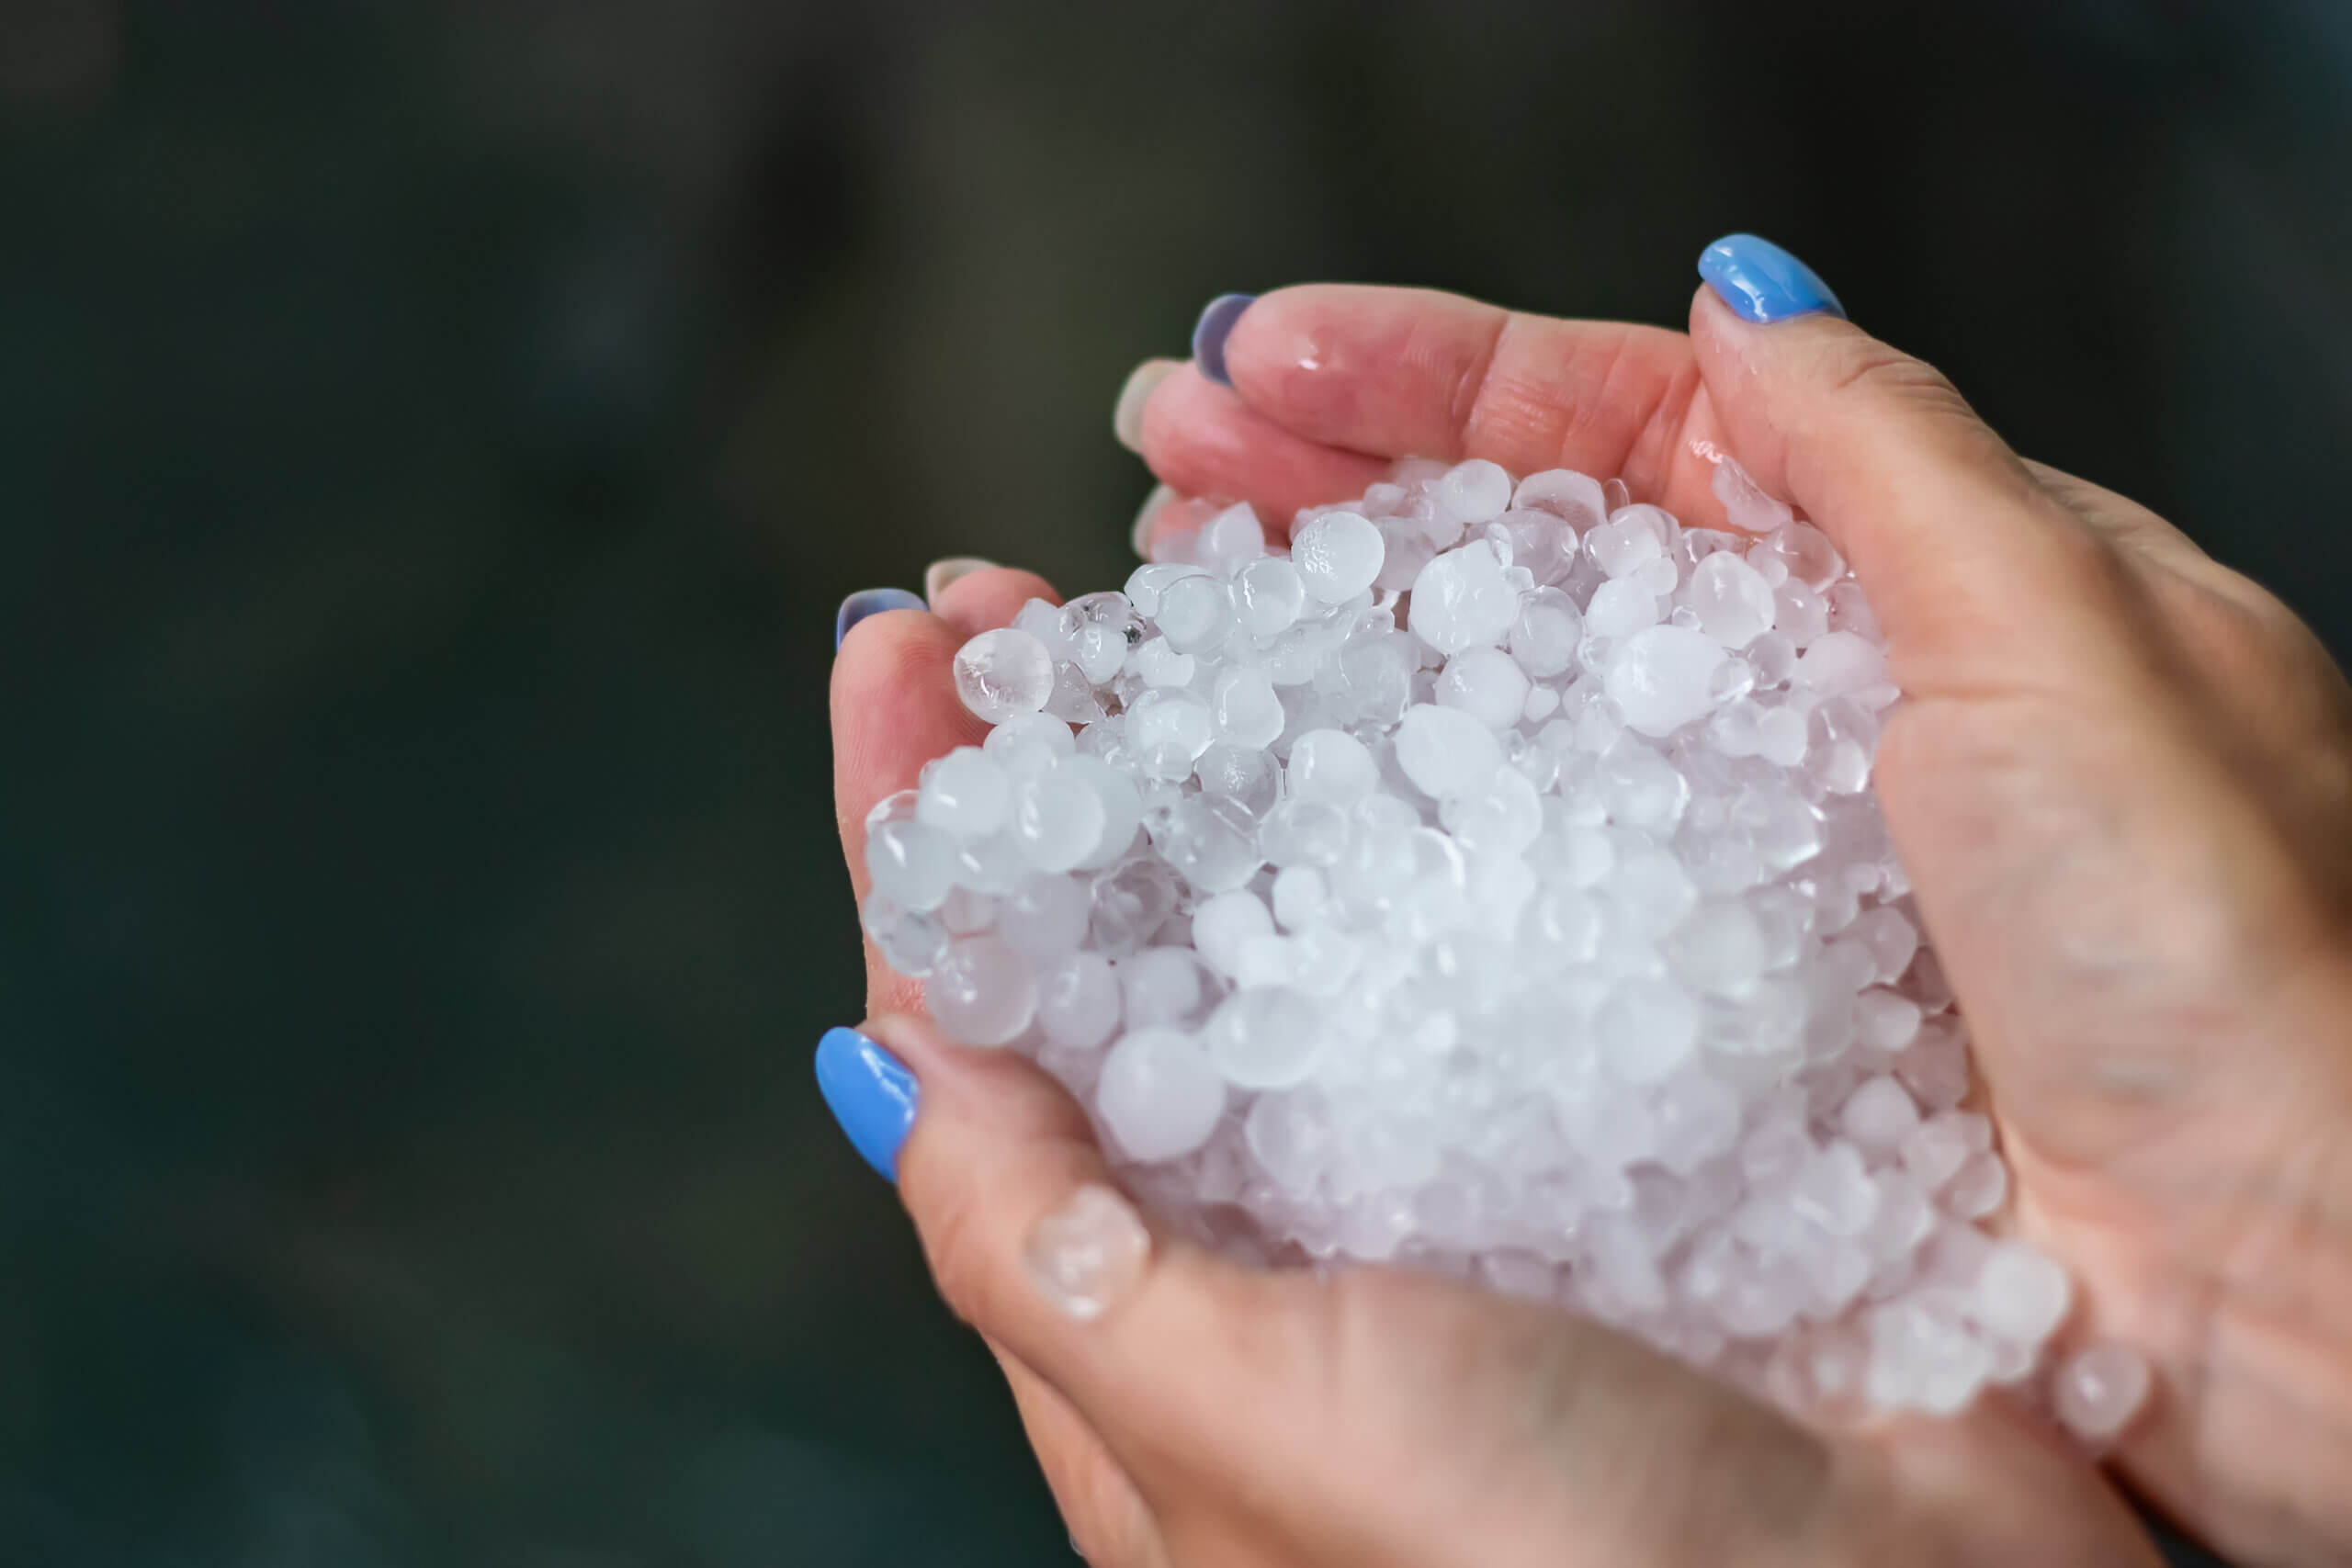
If you live here, you already know the sound. The sky goes gray. The wind shifts. Then it starts. And suddenly your roof, gutters, siding, and windows are all in the line of fire. Colorado ranks second in the U.S. for hail insurance claims, and our hail season is generally mid-April through mid-September. In other words, hail is not a “maybe” problem. It is a “when” problem. The good news is you can do a lot before the first big storm hits. So here’s a clear, practical guide to prepping for hail season in Colorado.
Why hail damage can sneak up on you
Hail damage is not always obvious right away. Yes, sometimes you see shredded screens and dented downspouts. However, roofs can take hits that create small cracks or bruises that show up later as leaks. Also, hail often comes with strong winds, which matters because wind can drive hail sideways and hitting places you don’t normally worry about, like window trim and siding.
Your hail-season checklist (before storms start)
1) Take some quick baseline photos
First, take clear photos of:
-
Roof lines (from the ground)
-
Gutters and downspouts
-
Window screens
-
Siding and garage door
-
Outdoor A/C unit
This should only take you ten minutes, but it can make insurance paperwork much easier later.
2) Clean gutters and downspouts
Clogged gutters can turn a hailstorm into a water problem fast. Water backs up, then it finds a way in. So clean them now, not during a hail warning. Also ensure downspout extensions are down and able to direct hail and water away from the foundation of the home.
3) Trim trees and look for loose branches
Branches snap more easily than you think. Plus, spring storms can bring strong gusts. A trimmed tree is less of a risk.
4) Secure or store “flying objects”
Before a potential storm, bring in or anchor:
-
Patio umbrellas
-
Lightweight chairs
-
Planters
-
Grill tools and covers
-
Trampolines (if you have one)
5) Review your insurance basics
A quick word about contractors and too-good-to-be-true offers
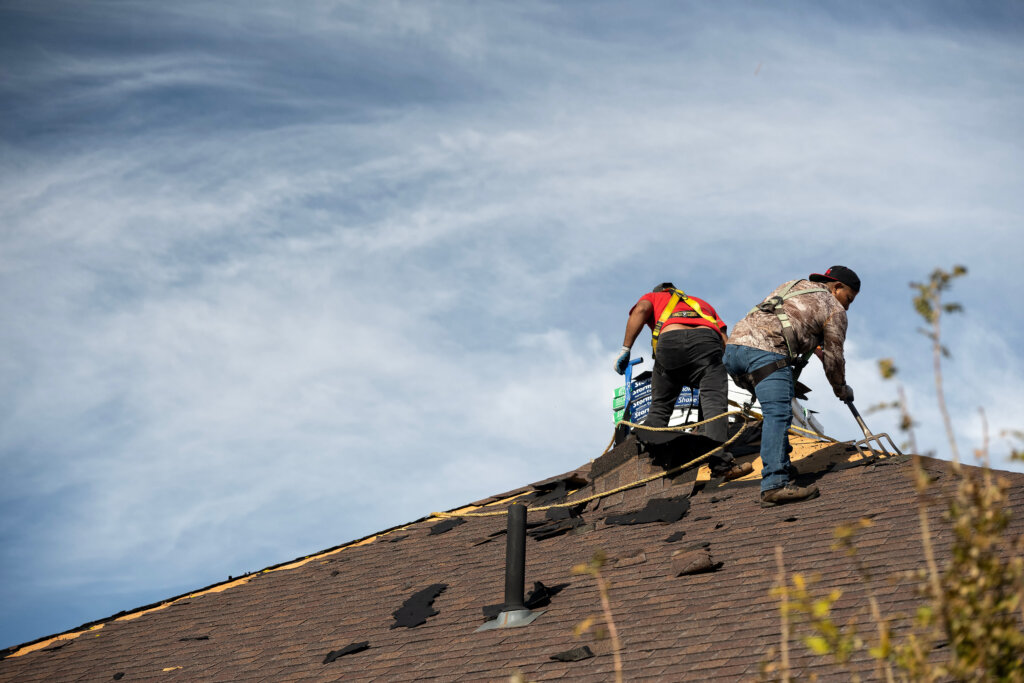
After a big hailstorm, door knockers tend to show up fast. Some are legitimate local contractors. Others are storm chasers who move from neighborhood to neighborhood and may be hard to track down later. So even if you want it handled immediately, it’s worth slowing down. Try to work with a licensed and insured contractor you trust, ideally someone with a local address and solid reviews. Ask who will actually do the work, what’s included, and what the payment schedule looks like. Then get the scope, timeline, and warranty in writing. And if anyone pressures you to sign on the spot, promises something that sounds free, or wants a big deposit before you understand the plan, take that as your cue to pause and compare options.
Challenger Homes: a home you can feel confident about
Hail season is part of living in Colorado. Still, the stress is optional. A few small steps now can reduce damage later, and they can save you a lot of time if you ever need to file a claim. And if you’re thinking about a move this year, it helps to start with a home you feel confident in. Challenger Homes communities are built for Colorado living, so you can spend more time enjoying your home, and less time worrying about what the next storm might bring. Contact us today to schedule a tour and to learn more.