Buying a home is a big deal! If you’ve been scrolling listings long enough, you’ve probably realized there are two very different paths to purchasing a home: resale or new construction. The good news is that the new construction home buying process is usually more structured than people expect. That’s because there’s a clear sequence from “first visit” to “front door” and you’re not guessing what happens next. Here are some benefits to the new construction home-buying process:
Why Buying New Can Be the Easier Choice
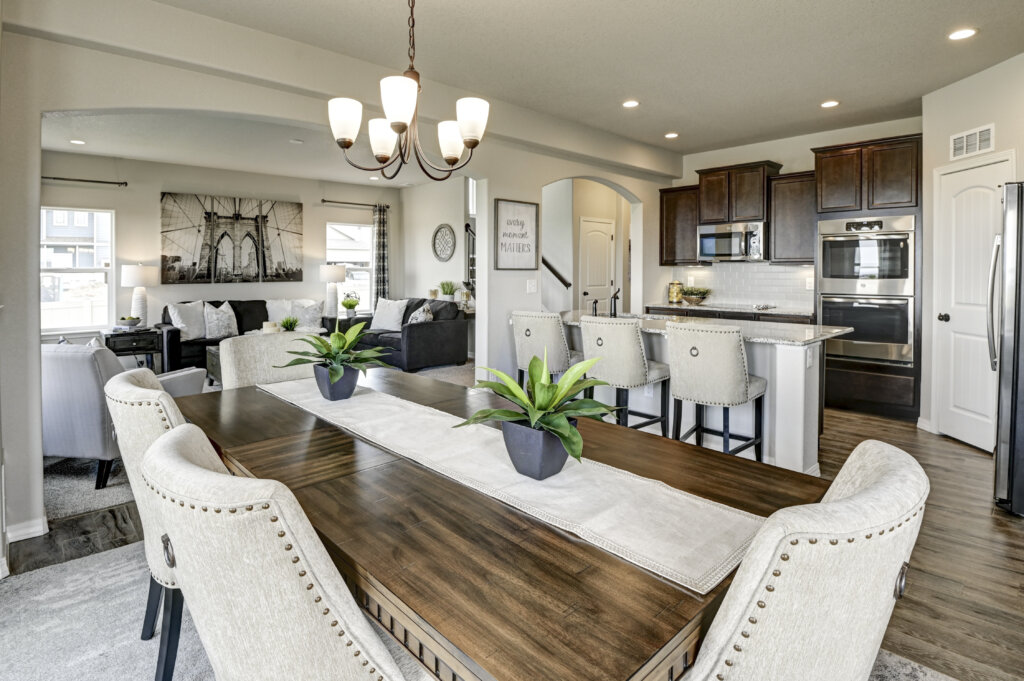
Here’s the part that doesn’t get said enough: buying new isn’t only about new finishes. It’s about starting with a home designed for how people live today with features like open layouts, flexible spaces, smart storage, and modern finishes. With a new construction home, you won’t be inheriting someone else’s outdated systems or surprise repairs. Challenger Homes builds with high-performance materials that support cleaner air and energy efficiency (think advanced insulation, low-VOC finishes, and efficient HVAC). And, every home comes with a comprehensive builder-backed warranty for extra peace of mind after move-in. Challenger Homes offers a free digital “Why Buy New” guide to walk you through the benefits of a new construction home over a re-sale home.
A Timeline for the New Construction Home-buying Process
1) Explore communities and floorplans
Start by touring models, comparing layouts, and narrowing in on what fits your lifestyle, whether that’s a home office, a larger garage, or space to spread out. One of the biggest perks of new construction is choice: you’re not just buying a house, you’re choosing a plan and a community that matches how you want to live.
2) Sign the purchase agreement
With new construction, signing earlier does more than reserve a home. It secures your price and locks in your homesite of choice. It also allows you to take advantage of special incentives, promotions and price reductions that are being offered at the time.
3) Secure financing
Challenger Homes partners with PenTrust Mortgage to help buyers navigate new-home financing. Getting pre-approved early can help you move faster once you’ve found the right fit. The are many options available to finance a new home purchase including traditional fixed-rate mortgage, adjustable rate mortgages, VA loans, and more.
4) Get construction updates
This is where new construction can feel surprisingly reassuring. Instead of wondering what’s happening behind the scenes, you’ll get regular updates as your home comes together — so the process feels transparent, not mysterious. Challenger Homes has dedicated sales staff to walk you through all the important milestones of a new home purchase.
5) Personalize your home with hand picked finish packages
You don’t need to be an interior designer to make a home feel like yours. Challenger Homes offers professionally curated finish packages (cohesive combinations of colors, materials, and finishes) that simplify decisions and help you get a polished look without spiraling into a million tiny choices. If your timeline is tight, a quick move-in home can give you the benefits of new with a shorter wait.
6) Final walkthrough
Before closing, you’ll walk the home with the team to go over warranties and get all your questions answered.
7) Closing day and move-in
Then comes the best part: stepping into a new home with modern comfort, quality, and peace of mind.
Ready to Get Started on Your New Construction Home Buying Process?
The best part of buying new is knowing what to expect — both in the process and in the home you’re moving into. If you’re ready to explore our Colorado Springs floorplans and communities (and see what new could look like for your next chapter) Challenger Homes is here to help you take the next step. Contact us today to learn more.